00Fraud detection infrastructure
Structured fraud. Structured defense.
Retix finds the fraud rings a single transaction can't reveal — graph mining and AI, catching organised fraud in payments in real time.
01Product
What we do
Organised fraud doesn't look like a single bad transaction. It looks like a shape — repeated across accounts and devices that share the same infrastructure. Retix finds that shape.
Retix treats a payment provider’s transaction data as a live graph — accounts and devices as nodes, transactions as edges — and searches it for the structures organised fraud leaves behind. A single transaction can look ordinary; the network it’s part of usually isn’t.
- Less fraud. Coordinated rings — shared-device networks, mule accounts, cash-out chains — get caught as a group, not one transaction at a time after the money has already moved.
- Fewer false positives. A payment that looks risky in isolation often looks routine once you see who else is connected to the same device or account, cutting reviews that would otherwise catch good customers.
- How: graph mining and AI. Incremental graph algorithms update the network picture as each payment arrives; anomaly detection on top flags structures that don’t belong — in real time, and in deeper batch passes over historical data.
- Layered on what you already run. Retix sits alongside a provider’s existing fraud stack rather than replacing it.
02Pilot
P2P Pilot Project
An active, publicly funded pilot with Vipps MobilePay and Aarhus University — testing real-time graph fraud detection on live P2P payment data.
Retix, Vipps MobilePay, and the Department of Computer Science at Aarhus University are running a joint pilot on Vipps MobilePay’s peer-to-peer payment traffic: production-representative data, domain expertise from Vipps MobilePay’s Risk Intelligence team, and the graph algorithms behind Retix, developed with the university’s research group.
- What’s being tested. Whether incremental graph algorithms and anomaly detection can flag organised fraud rings — shared devices, mule accounts, cash-out chains — as P2P payments happen, without slowing the payment down.
- Backed by published research, not a black box. The academic side is led by Prof. Ira Assent and Assoc. Prof. Davide Mottin, with Postdoc Kasper Overgaard Mortensen implementing the graph algorithms the pilot runs on.
- Publicly registered and funded. Fraud detection in payments runs 2026–2027, funded by DIREC (Digital Research Centre Denmark), with additional funding from Copenhagen Fintech for the P2P collaboration.
We’ll share key insights as we progress — this is what’s actually running today, not a roadmap.
Project data
- Project
- Fraud detection in payments
- Partners
- Retix, Vipps MobilePay, Aarhus University
- Funded by
- DIREC — Digital Research Centre Denmark, Copenhagen Fintech
- Period
- 2026–2027

03Regulation
PSD3/PSR shifts the losses onto you.
The EU's payment overhaul comes as a pair: PSD3 sets who may provide payment services, and the Payment Services Regulation (PSR) sets how they must fight fraud. Together they make providers liable for losses that today often land on the customer.
- Two instruments, and the PSR is the one with teeth. PSD3 is a directive that updates licensing and supervision, to be transposed into national law. The PSR applies directly in every member state and carries the fraud rules: payee-name verification, impersonation-fraud refunds, and liability when fraud prevention falls short.
- Liability is moving toward providers. Under the agreed PSR text, a provider that fails to operate appropriate fraud-prevention mechanisms covers its customers’ losses. Victims of scammers posing as bank staff are refunded in full once they report it to the police and their provider, and a provider that misses a payee-name/IBAN mismatch answers for the misdirected payment.
- Monitoring has to see behaviour, not single transactions. The PSR expects risk-sensitive, behavioural transaction monitoring, lets providers share fraud data under structured, GDPR-safeguarded arrangements, and requires the receiving provider to freeze payments it finds suspicious. Organised rings rarely stand out one payment at a time — they show up in how accounts, devices and payments connect.
- The losses are already large, and rising. Payment fraud across the EEA reached €4.2bn in 2024, up 17% on 2023 (EBA/ECB joint report). PSD3/PSR doesn’t create this fraud — it changes who absorbs it.
- The clock has started. Parliament and Council reached political agreement in November 2025, and formal adoption is close. The PSR applies 18 months after entry into force, with payee verification and its liability following at 24 months. Detection built to catch organised rings takes real time to stand up properly.
See where you stand before the liability shifts. We'll assess your current fraud-detection setup and quantify the headroom for reducing losses with Retix — no obligation.
Request an assessment04Team
Who's behind Retix
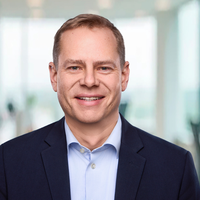
Anders Sandholm
Founder & CEO
18 years at Google — building Chrome, leading product for Dart, then seven years in Google Research using AI to fight spam and fraud, including billion-scale fraud-detection work at Google Payments. Ex-McKinsey. PhD in Computer Science (Aarhus University), MBA (INSEAD).
LinkedIn, Anders Sandholm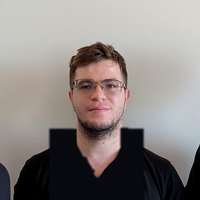
Mihai Rotaru
Software Engineer
Builds the engineering around the detection engine: data pipelines, simulated payment data for integration testing, and the path from research prototype to production. On the Vipps MobilePay pilot since kick-off, turning its integration requirements into working software.
LinkedIn, Mihai Rotaru
Kasper Overgaard Mortensen
Postdoc in Computer Science
Researcher at Aarhus University specialising in scalable graph algorithms and machine learning, published at VLDB and MLSys — including Sankofa (VLDB 2026) on real-time summaries of fast-changing graphs. Implements the graph algorithms the Vipps MobilePay pilot runs on.
LinkedIn, Kasper Overgaard Mortensen
05Ecosystem
Partners & supporters
Retix is backed by Danish public innovation funding and builds on research and infrastructure partnerships with universities and payments platforms. Click through any node to visit.